
Africa’s automotive opportunity is often discussed in terms of its population, mineral wealth and low vehicle ownership. Those factors matter, but they do not build an automotive industry on their own. The real opportunity lies in connecting African markets and industrial capabilities so that vehicles and components can be manufactured, traded and serviced competitively across the continent.
The African Continental Free Trade Area (AfCFTA) offers a framework for achieving this. By creating a larger integrated market, harmonising trade rules and encouraging regional production, it could help transform Africa’s automotive industry from a collection of fragmented national markets into a connected manufacturing ecosystem.
READ ALSO: BII Unveils New Africa Investment Strategy: Targets KSh864 Billion in Capital
The scale of the opportunity is considerable. A World Economic Forum analysis published in April 2023 projected that the AfCFTA could help generate an additional $12 billion for Africa’s automotive industry by 2027. The same analysis estimated the industry’s value at $30.44 billion in 2021, with a projected increase to $42.06 billion by 2027. These are earlier estimates and projections, but they illustrate the potential economic value of deeper continental integration.
Africa’s annual demand averages approximately 2.4 million passenger cars and 300,000 commercial vehicles, according to the World Economic Forum. Yet much of this demand is met through imports, particularly used vehicles, rather than locally manufactured products. This creates an industrial opportunity: a greater share of the vehicles and components consumed across Africa could be produced within the continent.
The production figures, however, reveal how much work remains. Africa manufactured approximately 1.23 million vehicles in 2025, representing about 1.3 per cent of global output of 96.4 million vehicles. South Africa produced 618,077 vehicles, while Morocco recorded 501,965. Together, the two countries accounted for more than 90 per cent of African production.
This concentration demonstrates that Africa has established manufacturing capabilities, but also highlights the limited participation of other economies in large-scale automotive production. Egypt, Algeria, Kenya and Ghana have opportunities to expand assembly and component manufacturing, although attracting sustained investment will depend on infrastructure, skills, policy consistency and access to regional markets.
The AfCFTA’s automotive framework seeks to address some of these structural constraints. Its Continental Automotive Strategy and Implementation Plan provide a basis for developing regional value chains, while rules of origin establish the conditions under which vehicles and components qualify for preferential treatment as African products.
Following the conclusion of automotive rules of origin, AfCFTA Secretary-General Wamkele Mene said in October 2026 that attention must shift towards translating the rules into investment, production and employment. The priorities include developing investment-ready projects, strengthening regional supplier networks and ensuring that production across different African markets is commercially viable.
This is particularly important because manufacturing a vehicle requires far more than assembling imported parts. It depends on networks of suppliers producing tyres, glass, plastics, batteries, electronics, textiles and other components. Connecting these suppliers across borders would allow African manufacturers to benefit from economies of scale while reducing dependence on external supply chains.
UNCTAD’s 2023 Economic Development in Africa Report illustrates the weakness of existing integration. Based on trade data for 2018–2020, African suppliers accounted for only 4 per cent of imports of automotive parts and systems, 11 per cent of non-specific components and 43 per cent of raw materials. The figures demonstrate that the continent has a stronger position in supplying raw materials than in producing more sophisticated automotive inputs.
Financing is another essential part of the equation. In October 2026, Afreximbank announced a US$1 billion facility to support local content development and investment in Africa’s automotive industry. The initiative is intended to strengthen manufacturing, regional supply chains, technology transfer and the development of automotive capabilities.
South Africa’s Minister of Trade, Industry and Competition, Parks Tau, has also outlined a longer-term ambition for Africa to produce between four million and five million vehicles annually by 2035, including new-energy vehicles and related components. A proposed automotive pact between the Southern African Customs Union and Egypt could further encourage cooperation between established and emerging manufacturing markets, promoting complementary production rather than fragmented competition.
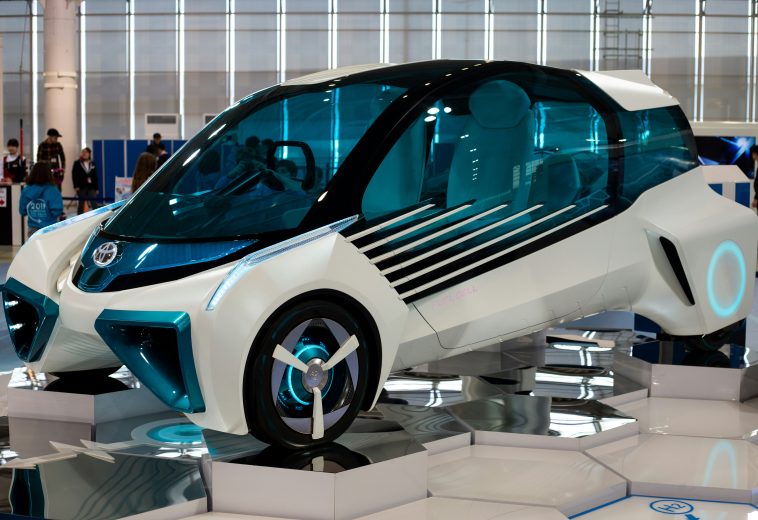
The transition towards electric mobility adds another dimension. Africa possesses significant reserves of minerals such as cobalt, lithium, copper and platinum, which are important to battery and vehicle technologies. However, the opportunity extends beyond extraction. Developing mineral processing, battery-component manufacturing, recycling and associated technologies would enable African economies to retain more value from their natural resources.
Electric mobility is still developing across the continent. In South Africa, battery-electric vehicles accounted for less than one per cent of new vehicle sales in 2025, while markets such as Egypt, Rwanda and Kenya are exploring different applications of electric transport. Expanding this sector will require affordable vehicles, reliable electricity, charging infrastructure and financing models suited to African consumers and businesses.
Affordability and safety must also remain central to the industry’s development. Used vehicles continue to provide essential mobility for households and businesses that cannot afford new cars. However, the importation of older, poorly maintained vehicles raises concerns about road safety, emissions and maintenance costs. UNEP has highlighted the importance of stronger vehicle import standards to ensure that affordability does not come at the expense of public safety and environmental protection.
Ultimately, the AfCFTA’s automotive framework offers a pathway towards continental integration, but trade agreements alone cannot build competitive industries. The decisive work lies in translating rules into predictable trade, investment into local capabilities and national manufacturing strengths into regional supply chains.
Success will be measured by more components sourced within Africa, competitive exports between African countries, skilled employment, safer vehicles and mobility solutions that more households can afford. As Minister Tau has emphasised, continental integration must support real factories, suppliers, jobs and exports.
The distance between Africa’s automotive potential and a functioning continental industry will be closed through bankable projects, reliable infrastructure, coordinated industrial policies and the patient development of supplier capabilities across borders. The opportunity is not simply to assemble more vehicles, but to establish an African automotive industry capable of creating value, competing globally and supporting the continent’s wider industrial transformation.