
Africa is maintaining economic momentum despite a slower global environment, with new data showing that the continent’s real gross domestic product grew faster than the global economy during the second quarter of 2026.
According to the International Monetary Fund (IMF), Africa’s real GDP increased by 1.6% in the second quarter, up from 1.3% in the first quarter. Global real GDP growth, meanwhile, stood at 0.7% during the same period.
READ ALSO: Lomé’s Energy Hub: Togo Secures Funding to Expand Regional Fuel Infrastructure
The figures provide an encouraging indication of the continent’s economic resilience at a time when economies worldwide are navigating slower growth and persistent investment pressures.
Recent reporting by Africanews also points to a rise in capital mobilisation across the continent. Citing World Bank figures, it reported that $22 billion in capital was mobilised in Africa with World Bank support in 2026, compared with approximately $9 billion in 2022.
The increase reflects growing attention to Africa’s infrastructure and development opportunities. Investment in areas such as energy, transport, digital infrastructure and strategic industries is increasingly being linked to the continent’s long-term economic transformation.
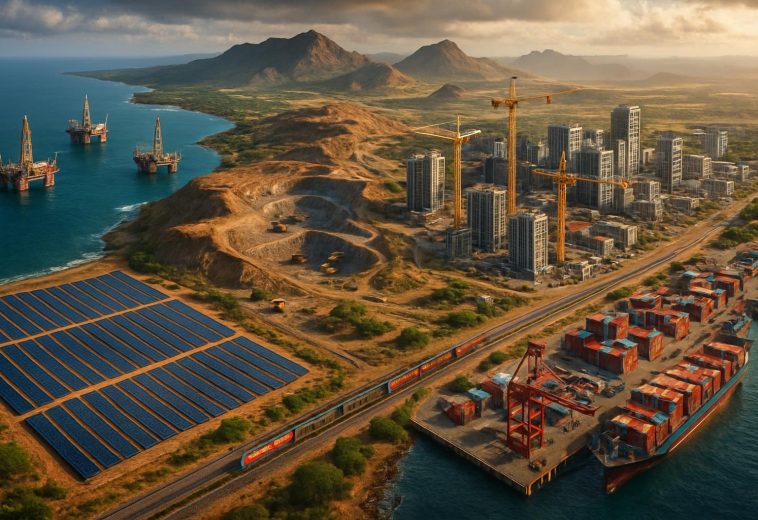
Infrastructure remains particularly important. Africa’s expanding population, urbanisation and industrial ambitions require major investment in electricity, transport networks, logistics, telecommunications and productive industries. Better infrastructure can reduce business costs, improve market access and strengthen connections between African economies.
Recent projects across the continent illustrate this trend. In Kenya, construction has begun on a $16 billion refinery in Lamu, designed to strengthen regional fuel supply and industrial capacity. In Côte d’Ivoire, the 52.4MW Ferké Solar project is expanding renewable electricity generation and is expected to produce more than 90 gigawatt-hours of electricity annually.
Such investments are significant because they can create economic activity beyond the infrastructure itself. Energy projects can support manufacturing and digital businesses, while transport infrastructure can make it easier for goods and services to move across borders.
Africa’s investment story, however, remains one of both opportunity and unfinished work. Africanews reported that the continent attracted only around 4% of global foreign direct investment in 2025. The African Development Bank has also estimated that more than $1.3 trillion is required annually to meet Africa’s development goals.
UN Trade and Development similarly reported that Africa attracted about $70 billion in foreign direct investment in 2025. While that was roughly one-third above the continent’s 2010–2024 average, investment remained concentrated in particular countries and sectors.
The challenge, therefore, is not simply attracting more capital but ensuring that investment contributes to productive capacity, skills, jobs, technology transfer and stronger African value chains.
The current growth figures suggest that the continent has a foundation on which to build. The combination of economic expansion, rising capital mobilisation and infrastructure development could strengthen Africa’s position in the global economy if investment continues to reach sectors capable of generating broad-based productivity.
For Africa, the next phase of economic transformation will depend not only on how much capital enters the continent, but on how effectively that capital is converted into infrastructure, businesses, skills and opportunities.
The latest numbers point to a continent continuing to build despite global headwinds — with investment and infrastructure increasingly central to the next chapter of Africa’s growth story.