
For many African small businesses, finding a buyer in another country can be easier than completing the sale. Questions around trust, export regulations, payment, trade finance, logistics and documentation can turn a promising cross-border opportunity into a missed one. As Africa moves towards deeper economic integration, closing these gaps is becoming just as important as opening markets.
A new partnership between the African Export-Import Bank (Afreximbank) and the East African Business Council (EABC) is seeking to address that challenge by giving businesses a more direct route into Africa’s growing trade ecosystem.
READ ALSO: CONTINENTAL CONNECTIVITY: BUILDING AFRICA’S TRADE ROUTES
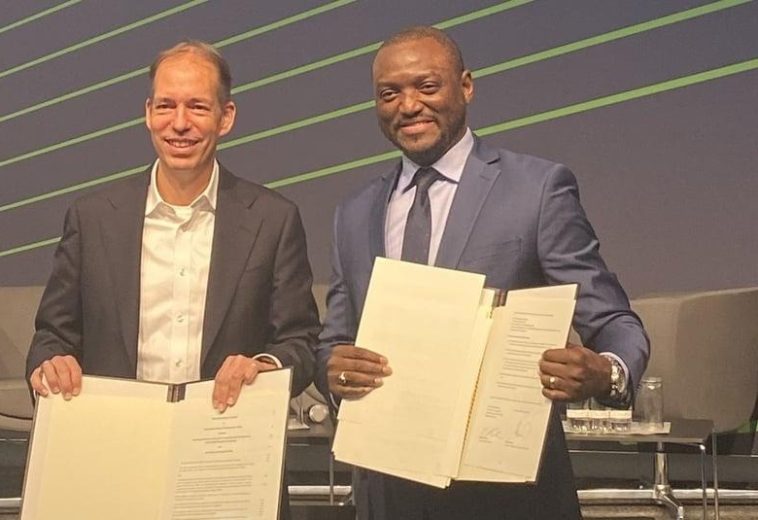
Signed in Nairobi during the inaugural East Africa CEO & Investment Forum, the agreement positions EABC as an onboarding agent for Afreximbank’s Africa Trade Gateway (ATG), helping businesses across East Africa connect with verified trading partners and trade-support services through a digital platform.
The opportunity is significant. The East African Community’s Common Market serves a population of roughly 300 million, while the African Continental Free Trade Area (AfCFTA) brings together a continental market of about 1.3 billion people. Yet the scale of the market has not always translated into equally strong levels of trade between African businesses.
According to recent estimates, intra-African trade accounts for only about 16 per cent of Africa’s total trade. Within the EAC, intra-regional trade accounts for roughly 15 per cent of the bloc’s total trade, despite growing by 27 per cent between June 2024 and June 2025.
The challenge, therefore, is no longer simply creating a market. It is making that market accessible to the businesses that need it most.
Turning Market Access Into Business Connections
The ATG was designed to help bridge this gap by connecting businesses with verified counterparties and services covering trade finance, payments, compliance, logistics and market intelligence.
Since its launch in June 2023, the platform has expanded across more than 45 African countries and, according to Afreximbank, connects 45 trade-supporting institutions, 110 commercial banks and 25,000 verified companies. Its reported pipeline of potential trade opportunities is valued at about US$4.5 billion.
These figures point to the scale of demand for better connections. But the more important question is what happens after a business finds a potential partner.
That is where the EABC partnership becomes particularly relevant.
EABC’s regional network can help businesses navigate the practical requirements of entering new African markets, including AfCFTA opportunities, rules of origin, tariff concessions, customs procedures and export requirements. For smaller firms, this kind of guidance can be decisive.
A digital platform may introduce a Kenyan manufacturer to a buyer in Tanzania, or a Ugandan agricultural producer to a distributor in Rwanda. But the transaction still requires the right documents, knowledge of customs procedures, appropriate payment mechanisms and confidence that both sides can fulfil their obligations.
The partnership therefore seeks to connect market access with the practical knowledge required to use it.
Why SMEs Stand to Gain
Large corporations often have the resources to maintain offices in several countries, employ legal and compliance teams and establish relationships with banks and logistics providers. Smaller companies rarely have the same advantages.
For an SME trying to export for the first time, simply identifying a credible buyer can be a major undertaking. The cost of researching markets, verifying partners and understanding regulations can consume time and resources that a small business cannot easily spare.
By bringing these functions closer together, the ATG could reduce some of the search and coordination costs that have historically made cross-border commerce more difficult for smaller enterprises.
Yet access to finance remains another critical piece of the equation.
A connection to a bank does not automatically translate into affordable credit. Many SMEs still struggle with limited collateral, short credit histories, weak financial records or insufficient documentation. For the digital trade ecosystem to deliver its full promise, financial institutions will need products that reflect the realities of smaller businesses, alongside mechanisms that can reduce lending risks.
This is where Afreximbank’s wider digital ecosystem becomes important.
The ATG complements platforms such as the Pan-African Payment and Settlement System (PAPSS), which supports cross-border payments in African currencies, and MANSA, Afreximbank’s centralised customer due diligence and KYC platform. Together, such systems are designed to address different parts of the same problem: making it easier for African businesses to identify one another, establish trust and complete transactions.
Beyond the Digital Marketplace
Digital connectivity, however, cannot solve every obstacle to African trade.
A business may find a buyer online and secure financing, only to encounter expensive freight, congested ports, unreliable electricity or inadequate transport infrastructure. The United Nations Economic Commission for Africa has estimated that infrastructure deficiencies can increase intra-African trade costs by 30–40 per cent.
That reality makes the ATG an important enabler, rather than a standalone solution.
Its success should ultimately be judged not only by the number of companies registered or opportunities listed, but by the transactions that follow. How many SMEs secure new buyers? How much finance is actually disbursed? How many potential opportunities become completed exports? And how many businesses return to the platform to trade again?
Those measures will reveal whether digital connectivity is translating into sustainable commercial relationships.
For East African SMEs, the Afreximbank–EABC partnership offers a practical bridge between the promise of African integration and the realities of doing business across borders. By connecting enterprises to potential partners, market information, finance and trade-support services, it can help make Africa’s expanding market more accessible to the businesses that form its economic backbone.
The wider opportunity is even greater. If digital platforms, financial systems and regional business networks can work together effectively, Africa’s integration agenda can move beyond agreements and frameworks towards something businesses can experience directly: more buyers, more suppliers, more investment and more African products moving across African borders.