
Africa’s financial inclusion story is entering a new phase as technology, banking and sustainable finance increasingly converge to expand access to capital for individuals, microenterprises and small businesses.
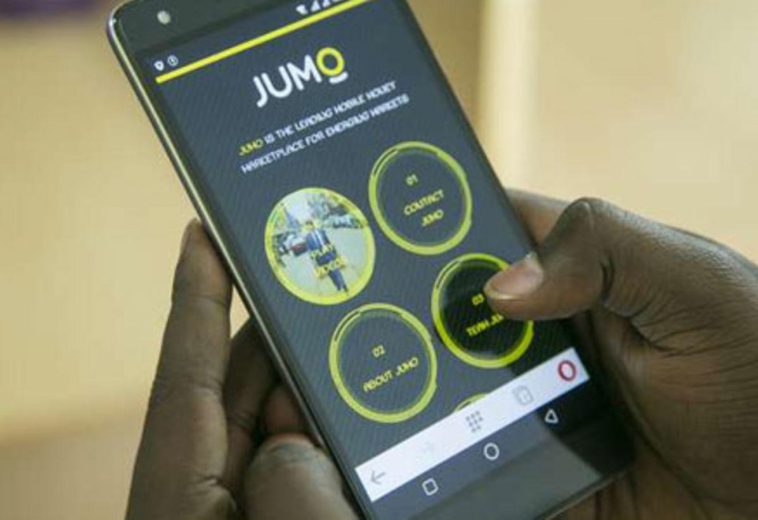
A recent development involving financial technology company JUMO and Standard Bank Group illustrates this shift. The two organisations have launched a Social Finance Framework designed to mobilise sustainable funding for inclusive lending across nine African markets. The framework creates a structure through which social loans and bonds can support financing for underserved individuals, microenterprises and small and medium-sized enterprises.
READ ALSO: Dangote Refinery IPO: A New Chapter for African Capital
The significance extends beyond one financial framework. Across Africa, access to affordable finance remains a major determinant of whether entrepreneurs can start businesses, expand operations, hire workers or invest in productive assets.
Small businesses form a critical part of African economies, yet many operate outside traditional banking systems or struggle to meet conventional lending requirements. Limited credit histories, insufficient collateral, high transaction costs and informal business structures can make conventional borrowing difficult.
Digital financial technology offers a potential way around some of these barriers.
Technology-driven lending platforms can use alternative data, automated systems and digital transactions to assess customers who may not fit traditional banking models. When supported by responsible lending practices and appropriate regulation, this can widen access to financial services while reducing some of the costs associated with serving smaller borrowers.
The new framework is therefore significant because it seeks to connect digital finance with institutional capital. Rather than relying exclusively on conventional commercial lending, social-finance structures can provide investors with a framework for directing capital towards activities that generate measurable social and economic outcomes.
For Africa, that connection is particularly important.
Financial inclusion should not be viewed simply as the ability to open a bank account or make a digital payment. The deeper objective is productive financial participation: enabling people and businesses to obtain the capital they need to invest, grow and contribute to economic activity.
Microenterprises and SMEs are especially important in this equation. Access to working capital can help a small manufacturer purchase equipment, enable a retailer to expand inventory, support an agricultural enterprise through a production cycle or allow a young technology company to hire additional workers.
At continental level, the growth of digital finance also supports Africa’s broader integration agenda.
The African Continental Free Trade Area is intended to create a larger market for African businesses, but businesses need financial systems capable of supporting cross-border commerce. Digital payments, accessible credit and interoperable financial infrastructure can help entrepreneurs take advantage of opportunities beyond their domestic markets.
The potential is especially significant for women and young entrepreneurs, who can face additional barriers in accessing formal finance. Expanding responsible digital lending could help narrow some of these gaps, provided that affordability, consumer protection and financial literacy remain central to implementation.
There are, however, important safeguards.
Rapid expansion of digital credit without adequate consumer protection can create new vulnerabilities, particularly among borrowers with limited financial literacy. Data privacy, transparent pricing, responsible debt assessment and effective regulation must therefore develop alongside technological innovation.
African policymakers and financial institutions also need to ensure that digital finance does not become concentrated in a handful of markets. Building interoperable systems and supporting local fintech ecosystems can help spread the benefits across regions.
The emergence of social-finance structures suggests that Africa’s financial inclusion agenda is gradually moving from access towards scale.
The objective is no longer simply to bring more people into the financial system. It is to connect underserved communities and businesses with capital that can support economic activity, entrepreneurship and resilience.
If that momentum continues, Africa’s digital finance revolution could become an increasingly important pillar of inclusive economic growth — helping transform millions of underserved customers from recipients of financial services into active participants in the continent’s economic expansion.