
Africa’s trade integration is about more than lowering tariffs. It also requires making it easier for a business in one African country to pay a supplier in another. Cross-border payments can involve currency conversions, multiple financial intermediaries, compliance checks and delays. These costs affect smaller businesses particularly strongly, limiting their ability to participate in regional markets.
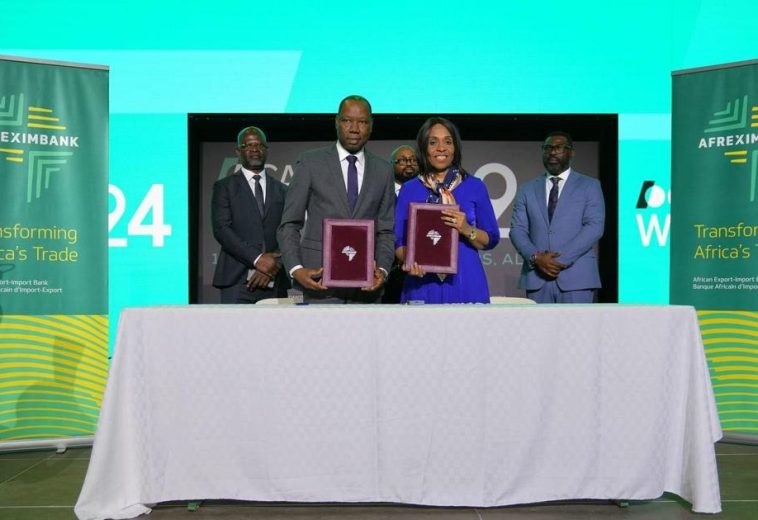
The Pan-African Payment and Settlement System (PAPSS) is seeking to address this challenge by enabling cross-border payments in local African currencies. Its expansion and growing transaction activity suggest that the continent is making progress towards a more connected financial infrastructure, although the broader economic benefits will depend on adoption, affordability and the growth of intra-African trade.
READ ALSO: Trade Finance: Expanding Capital Access for African Businesses
PAPSS reported an approximately 1,000 per cent increase in transaction volumes between comparable periods in 2025 and 2026, while transaction values increased by about 120 per cent. Nigeria recorded even stronger growth, with transaction volumes rising by approximately 1,100 per cent and values by 125 per cent. These figures, disclosed by PAPSS leadership in September 2026, indicate expanding use of the platform, although they do not represent full-year growth rates.
The network now operates in more than 30 African countries, connecting 24 central banks and over 200 commercial banks and payment service providers. It also works with 16 payment switches, while partnerships extend its reach to more than 300 financial institutions. PAPSS has indicated an ambition to expand its coverage further, with approximately 38 countries targeted by the end of 2026.
However, geographical connection does not automatically mean universal access. The practical availability of the service depends on participating banks, supported payment corridors, local regulatory approval and the readiness of financial institutions to process transactions.
The system’s underlying value lies in its settlement model. Under conventional cross-border arrangements, payments between African countries may pass through correspondent banks and international financial centres, often requiring conversion into major international currencies before reaching their destinations. PAPSS provides an alternative by allowing a payer to initiate a transaction in one African currency while the beneficiary receives payment in another, subject to participating institutions and available settlement arrangements.
Afreximbank has highlighted potential transaction-cost savings of approximately 92 to 95 per cent through the infrastructure. These are institutional estimates and should not be interpreted as guaranteed savings for every transaction. Actual costs depend on participating banks, foreign-exchange pricing, fees and the payment corridor involved.
The wider trade context explains why this infrastructure matters. Intra-African trade remains a relatively small share of the continent’s total trade, reflecting structural challenges that extend well beyond payments. Limited industrial supply chains, inadequate transport infrastructure, regulatory differences and non-tariff barriers continue to restrict the movement of goods between African markets.
The United Nations Economic Commission for Africa estimates that full implementation of the African Continental Free Trade Area (AfCFTA), including tariff liberalisation and the reduction of non-tariff barriers, could increase intra-African trade by approximately 45 per cent, equivalent to US$275.7 billion, by 2045. Efficient payment systems are an important part of making that opportunity commercially achievable.
PAPSS is not the continent’s only payment integration initiative. Regional platforms have already established important foundations for cross-border settlement. The Southern African Development Community Real-Time Gross Settlement System (SADC-RTGS), for example, connects participating central banks and financial institutions across 15 member states. The introduction of the Angolan kwanza into the system represents another step towards expanding the use of regional currencies in settlement.
In 2025, transactions involving Angola and the other 14 SADC countries amounted to approximately US$3.77 billion across nine currencies. The figures demonstrate the scale of regional financial activity while also revealing the concentration of transactions: South Africa accounted for approximately US$2.99 billion of the reported value.
East Africa’s experience provides a further illustration of the difference between infrastructure availability and actual usage. According to the Bank of Tanzania’s National Payment Systems Annual Report 2025, Tanzanian-shilling transactions through the East African Payment System (EAPS) declined by 4.43 per cent in volume and 18.90 per cent in value during 2025. The Bank attributed the decline partly to increased use of alternative channels, including SWIFT and mobile payments, as well as limited awareness.
Kenyan-shilling transactions through EAPS increased by 21.12 per cent in volume, while Ugandan-shilling transactions recorded a modest increase. The contrasting results suggest that regional payment platforms require more than technical connectivity. Banks and businesses must find them accessible, competitive and convenient enough to use regularly.
Currency liquidity presents another challenge. A payment platform can route instructions and facilitate settlement, but it cannot create demand for a currency or guarantee that participating banks have sufficient balances. Where trade between two countries is uneven, one country may accumulate the currency of its trading partner without having enough imports or investment opportunities to use it. Settlement arrangements must therefore address liquidity management, currency conversion and the distribution of financial risks.
Regulatory coordination is equally important. Financial institutions must comply with requirements covering customer identification, anti-money laundering, fraud prevention and sanctions screening. Differences in national regulations can complicate cross-border transactions, making interoperable systems and consistent supervisory standards essential. Digital identity solutions can support verification, but they do not eliminate the legal responsibilities of participating financial institutions.
For PAPSS, the next stage of development should therefore be measured not simply by the number of connected countries and banks, but by the quality and depth of actual usage. Relevant indicators include transaction volumes and values, the total cost of sending and receiving payments, settlement reliability, the participation of small businesses, foreign-exchange liquidity and the number of African companies using the platform to expand regional trade.
PAPSS and regional payment networks are addressing an important obstacle to continental integration: the difficulty of moving money across African borders efficiently. Their contribution will be strongest when they make settlement faster, more predictable and affordable for businesses of different sizes.
However, payment infrastructure cannot independently create productive capacity, transport links, balanced trade or affordable finance. The larger opportunity lies in connecting these systems with the AfCFTA’s wider industrial and commercial objectives. If African countries strengthen regulatory cooperation, improve currency liquidity and encourage greater participation by businesses and financial institutions, cross-border payments can become a more reliable foundation for regional trade and economic integration.